Luxury condo prices are driven by the interaction of location, building quality, amenities, ownership costs, and market conditions. A desirable address and well-managed building can support a premium, while high fees, deferred maintenance, limited financing, or weaker demand can pull values down. The National Association of Realtors reported that the median existing-condo and co-op price in the United States was $361,600 in 2023, but that national figure masks substantial differences between luxury markets and individual buildings. Understanding the forces behind those differences helps buyers assess value, owners plan improvements, and sellers price realistically.
How Location and Property Attributes Drive Luxury Condo Prices
A luxury condo is a privately owned residential unit in a condominium development positioned or equipped to command a premium, often through its location, design, services, views, or shared facilities. There is no single national price threshold that defines “luxury”; the label depends on the local market and the property’s relative quality. The price of an individual unit is the amount buyers are willing and able to pay, shaped by both its features and the broader conditions affecting comparable properties.
The National Association of Realtors (NAR) reported a 2023 median price of $361,600 for existing condos and co-ops nationally. That benchmark is useful for context, not as a luxury valuation: premium units in major urban and resort markets can sell for many times the national median. In practice, buyers and appraisers compare similar units in the same neighborhood and building, adjusting for floor, views, size, condition, and carrying costs.
Location, neighborhood access, and views
Location is the bundle of a condo’s geographic position and its access to employment, transport, schools, shops, cultural venues, parks, and recreation. In the luxury segment, a waterfront setting, recognizable city address, walkability, or unobstructed skyline can distinguish one unit from otherwise similar homes. Those advantages are not automatic: noise, traffic, environmental exposure, or difficult access can offset them.
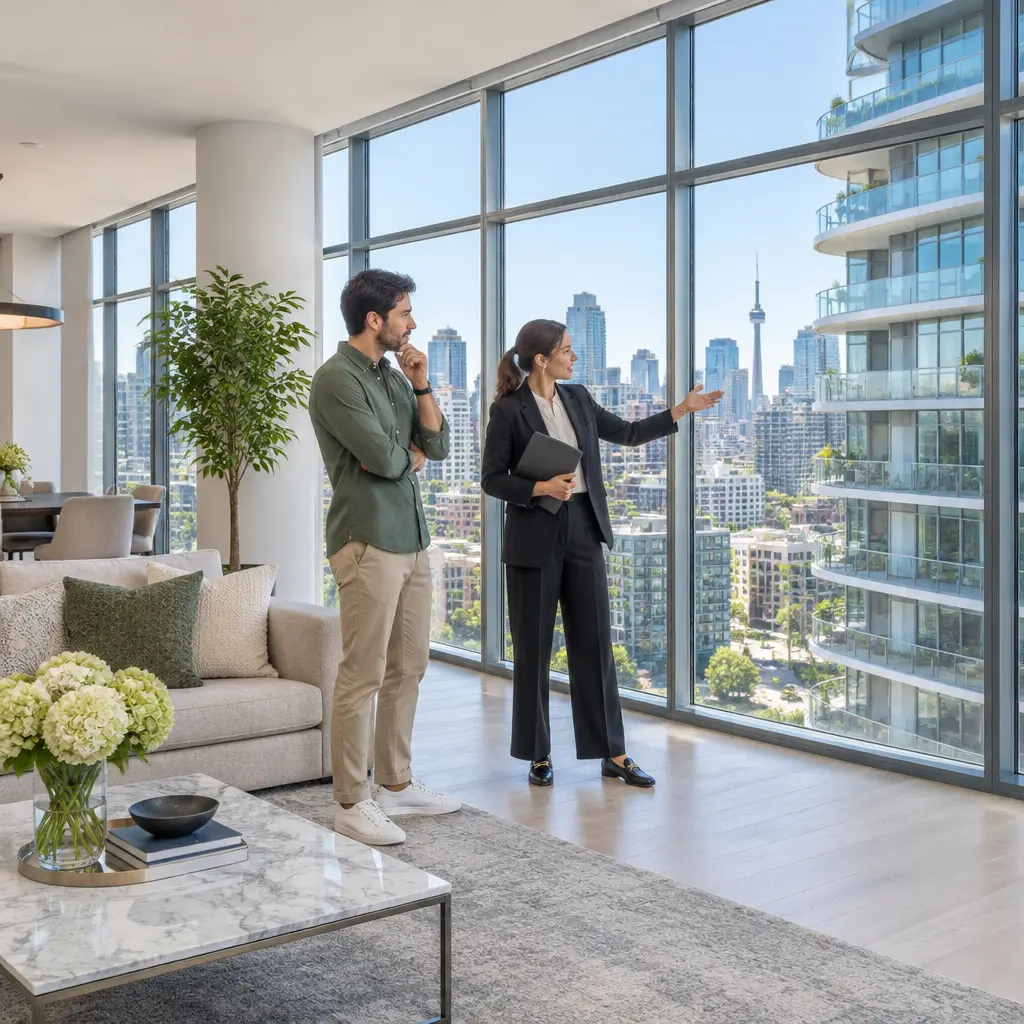
A view is a unit-specific amenity, and its value depends on quality, permanence, and demand. A broad ocean or park outlook may attract a premium over a blocked or lower-floor view, while construction on nearby land can threaten that premium. Buyers should check zoning and development plans, not assume that today’s view will remain unchanged. The Urban Land Institute’s research on walkable urban places also highlights the importance of access and neighborhood amenities in shaping real estate demand, though the precise price effect varies by market.
Unit design, floor, and usable space
Unit attributes include interior size and layout, ceiling height, natural light, outdoor space, privacy, storage, finishes, and the unit’s position within the building. A corner unit with a terrace and functional floor plan may outperform a larger but poorly laid-out unit. Luxury buyers often value quality and usability more than raw square footage, so comparisons should account for bedrooms, bathrooms, outdoor areas, and renovation needs.
The Appraisal Institute’s valuation principles emphasize comparison with relevant sales and adjustments for property differences. This is why a building’s average price per square foot is only a starting point: it can conceal meaningful variation between penthouses, renovated units, lower floors, and residences with different exposures.
Building reputation and scarcity
Building reputation reflects design, construction quality, management, security, service, and the experience of living there. A well-maintained property with responsive management and a strong record of upkeep can reassure buyers and support resale demand. Scarcity can add another layer: a small supply of residences with a particular waterfront position, architectural identity, or level of service may compete for a limited pool of buyers.
Scarcity supports prices only when buyers continue to value the distinguishing feature. A famous address cannot compensate indefinitely for poor maintenance, excessive expenses, or a location losing appeal. This connects physical property attributes with the building’s operating and financial condition.
How Amenities and Building Costs Affect Luxury Condo Prices
Amenities are shared facilities and services offered by a condominium, while carrying costs are recurring expenses owners pay to occupy and maintain their units. Both influence affordability and buyer demand. A pool, concierge, fitness center, valet, or private dining room may distinguish a luxury building, but buyers also consider the monthly assessment, utilities, taxes, insurance, and the likelihood of future special assessments.
Amenities and service levels
Amenities can include staffed entrances, security, gyms, pools, spas, lounges, landscaped grounds, guest suites, and package services. Their value depends on actual use, quality, accessibility, and upkeep—not simply the number of facilities advertised. A well-run concierge service may matter more to a buyer than an elaborate amenity space that is rarely used.
Amenities also create operating expenses. The National Association of Home Builders has documented the importance of shared features and community facilities in housing preferences, but a specific amenity’s impact on resale prices is local and difficult to isolate. Buyers should compare the building’s services with the monthly fees and review whether reserves are sufficient to maintain them.
Condo fees, reserves, and special assessments
Condominium fees fund shared operations and maintenance, which may include staffing, insurance, utilities, repairs, and reserve contributions. High fees can reduce the number of buyers able to qualify for a purchase or willing to pay a premium, especially when comparable buildings offer similar services for less. Low fees are not necessarily a bargain: they may indicate underfunded reserves or postponed maintenance.
The Community Associations Institute describes reserve funding as money set aside for major repairs and replacement of common elements. Buyers should review budgets, reserve studies, meeting minutes, insurance coverage, and planned projects. A special assessment—a one-time charge to owners for major costs—can affect both affordability and marketability, particularly if a building has substantial repair needs.
Building condition, safety, and insurance
Building condition includes structural integrity, roofs, façades, elevators, plumbing, electrical systems, and fire and life-safety equipment. Major deterioration can lower prices directly through repair costs and indirectly by weakening buyer confidence. In Florida, the 2021 collapse of Champlain Towers South in Surfside prompted heightened scrutiny of inspections, reserves, and structural maintenance, illustrating how safety concerns can influence perceptions of condominium risk beyond a single property.
Insurance availability and premiums also affect ownership costs. The Federal Insurance Office has reported growing affordability and availability challenges in parts of the U.S. property insurance market. For condo buyers, the relevant questions include what the association’s policy covers, the size of deductibles, whether owners need separate coverage, and how natural hazards may affect future premiums or insurability.
How Financing and Market Conditions Move Luxury Condo Prices
Market conditions describe the balance of buyers and available homes, along with the economic and financial factors shaping what purchasers can pay. Interest rates, lending rules, employment, income, new construction, investor demand, and consumer confidence can move luxury condo prices even when a particular unit has not changed. Because high-end buyers may rely on jumbo loans or substantial cash, luxury demand can respond differently from the broader housing market.
Mortgage rates and buyer purchasing power
Mortgage rates affect the monthly cost of borrowing and therefore the amount a financed buyer can afford. Freddie Mac’s Primary Mortgage Market Survey showed the average 30-year fixed mortgage rate reaching 7.79% in October 2023, its highest level in more than two decades at that time. Higher rates can reduce qualified demand, encourage buyers to postpone purchases, or lead them to seek lower-priced units.
The effect is not uniform. Some luxury purchasers pay cash, while others use financing, and jumbo-loan terms may differ from conventional mortgage terms. Lenders may also scrutinize the condominium association’s finances, insurance, litigation, and physical condition. If a project is difficult to finance, the pool of potential buyers can shrink even when the unit itself is attractive.
Supply, new construction, and comparable sales
Supply is the number of homes available to buyers, including new developments and resale listings. When comparable luxury units are scarce and demand is strong, sellers may have more negotiating power. A surge of new high-end projects, by contrast, gives buyers alternatives and may require existing buildings to compete through pricing, renovations, or improved services.
Comparable sales—recent transactions for similar properties—help establish a realistic price range. The NAR and the National Association of Home Builders track housing activity and construction trends, while local multiple listing services provide neighborhood-level evidence. Asking prices alone are not proof of market value; closed sales, days on market, price reductions, and inventory provide a more useful picture.
Economic confidence and luxury-buyer demand
Luxury demand is influenced by employment, business conditions, investment performance, wealth, and confidence about future income. These factors can matter especially in markets with a large share of second homes or internationally mobile buyers. Currency movements, tax rules, travel access, and local policy can also shape demand, but their effects vary by place and buyer group.
A useful example is the sharp contrast between a well-located, professionally managed building with limited competing supply and a similar-priced property facing high fees, insurance uncertainty, or major repairs. Even when both are described as luxury condos, buyers may treat them as very different investments because the second carries greater ownership risk.
How Buyers and Owners Can Evaluate Luxury Condo Value
A disciplined valuation considers the unit, the building, and the market together. No single feature—such as a prestigious address or a low fee—determines value by itself. The following checks help distinguish durable advantages from risks that may be reflected poorly in an asking price.
- Compare recent closed sales in the same building and nearby properties, adjusting for floor, view, condition, layout, and outdoor space.
- Calculate total ownership costs, including association fees, property taxes, insurance, utilities, financing, and likely assessments.
- Review association budgets, reserve studies, meeting minutes, insurance documents, inspection reports, and records of planned repairs.
- Assess whether amenities are maintained and actively valued by likely future buyers.
- Investigate neighborhood development plans, hazard exposure, transit access, and changes that could affect views or convenience.
- Ask a local real-estate professional, attorney, lender, and qualified inspector to evaluate issues within their expertise.
Conclusion: What Drives Luxury Condo Prices Up or Down
Luxury condo prices rise when location, views, unit quality, building reputation, useful amenities, and limited supply align with strong buyer demand. They can fall when financing becomes more expensive, competing inventory increases, recurring costs climb, or a building faces repair, insurance, safety, or management concerns. The NAR’s 2023 national condo and co-op median of $361,600 provides broad context, but a meaningful valuation requires local and building-level evidence.
For buyers and owners, the practical next step is to compare completed sales and scrutinize the condominium association’s financial and physical condition before making a decision. Further reading from NAR, Freddie Mac, the Community Associations Institute, and the relevant local building and insurance authorities can help clarify market trends and ownership risks.
Sources: National Association of Realtors, 2023 Existing-Home Sales Data, https://www.nar.realtor/research-and-statistics/housing-statistics/existing-home-sales; Urban Land Institute, The WalkUP Wake-Up Call: Boston, https://knowledge.uli.org/reports/research-reports/2017/the-walkup-wake-up-call-boston; Appraisal Institute, The Appraisal of Real Estate, https://www.appraisalinstitute.org/education; National Association of Home Builders, What Home Buyers Really Want, https://www.nahb.org/news-and-economics/housing-economics/special-studies/what-home-buyers-really-want; Community Associations Institute, Reserve Studies and Reserve Funding, https://www.caionline.org/Advocacy/Priorities/Reserve-Studies/; National Institute of Standards and Technology, Champlain Towers South Investigation, https://www.nist.gov/disaster-failure-studies/champlain-towers-south-collapse-investigation; Federal Insurance Office, Annual Report on the Effect of Big Data on the Availability and Affordability of Insurance, https://home.treasury.gov/policy-issues/financial-markets-financial-institutions-and-fiscal-service/federal-insurance-office; Freddie Mac, Primary Mortgage Market Survey, https://www.freddiemac.com/pmms; National Association of Home Builders, Housing Market Data, https://www.nahb.org/news-and-economics/housing-economics.